California High-Speed Rail Faces $680,500 in Questioned Consultant Travel Costs
California’s high-speed-rail inspector general found that $680,500 in consultant travel reimbursements lacked documented advance approval, according to accounts of the September investigation. The review covered about $1.15 million of more than $2 million paid in travel-related costs to four consulting firms during two fiscal years.
The numbers require an important distinction. The $680,500 represents payments made without the required prior documented approval; it is not a finding that every dollar was fraudulent or ultimately unrelated to state work. Separately, investigators identified $592,900 in expenses as unallowable under state regulations or contract terms. The authority has said it takes the findings seriously, plans to tighten its controls and will seek to recover improper costs that are identified.
The control failure matters more than the destinations
Some flagged claims involved upgraded flights, international travel, premium rideshares and trips associated with gyms, an escape room, a nightclub, a tiki bar and a cigar lounge. One set of premium rideshare charges covered travel to and from a restaurant, bar and nightclub between 9:40 p.m. and 2:30 a.m. Those details attract attention, but the central contract-administration problem is more basic: the authority often paid invoices without a documented decision that travel was necessary, authorized and cost-effective.
Travel controls on a major engineering program are not merely clerical. They establish who may order a trip, why physical attendance is required, which rates are permitted and what evidence must accompany an invoice. Advance approval gives a contract manager the opportunity to compare an in-person visit with a remote meeting, reject premium transportation or require a lower-cost booking. Reviewing an expense only after travel has occurred weakens that leverage because the cost has already been incurred and submitted for payment.
The investigation also found vague explanations such as routine weekly travel or digital-engineering meetings. That limits more than expense auditing. Large infrastructure programs rely on traceable decisions across designers, lawyers, financial advisers, program managers and construction contractors. If the authority cannot document why consultant travel was needed, it becomes harder to judge whether outside services are being deployed efficiently or whether contract ceilings and staffing arrangements reflect the work actually required.
A small fraction can reveal a large management exposure
Approximately $680,000 is small beside a rail program whose full San Francisco-to-Los Angeles cost has been estimated at roughly $126 billion to $230 billion. That comparison does not make the travel issue immaterial. Auditors reviewed only about $1.15 million of more than $2 million in travel expenses involving four firms, and roughly 60% of the reviewed payments lacked documented advance approval. The percentage makes the control weakness more consequential than the absolute amount alone.
Nor does this finding establish that the same weakness affects construction invoices, change orders or engineering work. Extending it to those areas without an audit would be speculation. It does, however, show why sampling, approval records and recoverability clauses matter: relatively modest expense claims can test whether a public owner is consistently enforcing the terms it already negotiated.
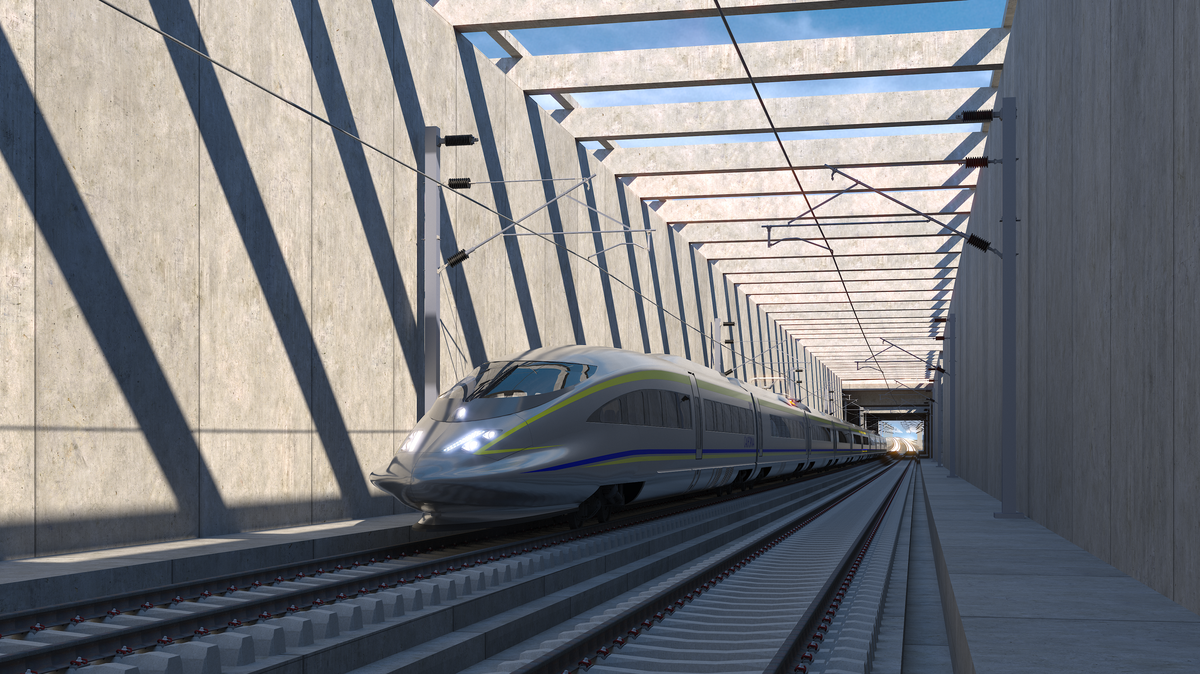
The timing intensifies the public-cost concern. Voters approved the project in 2008 after it was presented as a $33 billion Los Angeles-to-San Francisco system expected by 2020. Passenger service has not begun, no high-speed track has yet been laid, and current planning remains centered on the Merced-to-Bakersfield segment. Recent public accounts place potential statewide completion costs between about $126 billion and $230 billion, while the inspector general has separately warned of near-term funding pressure.
For taxpayers, weak expense review raises a fairness question: consultants should not receive reimbursement on looser terms than state rules and their contracts allow. For prospective passengers and Central Valley communities, the practical tradeoff is delivery capacity. Every management hour spent reconstructing approvals or disputing old invoices is an hour unavailable for property, utility, design, construction and systems-integration decisions. Recovering improper travel costs will not close a multibillion-dollar funding gap, but reliable controls are part of demonstrating that additional public money can be administered effectively.
What correction should look like
The inspector general recommended stronger approval and documentation requirements, defined consultant office locations, a uniform travel-request process, an audit of the four firms’ claims and recovery of unallowable expenses. The authority agreed to implement or partially implement corrective actions between late 2026 and March 2027, including more rigorous review and efforts to recover improper costs. It did not fully accept the inspector general’s position that each consultant trip must be justified, leaving a material disagreement over what adequate oversight requires.
The next meaningful test is therefore not another statement of concern. It is whether the authority can document that travel is approved before it occurs, demonstrate that exceptions are justified, identify recoverable payments and show that contract managers can reject executive-requested travel when required information is missing. The inspector general plans a follow-up evaluation after March 2027, when those controls can be measured against actual invoices rather than promised procedures.
| More aerospace and engineering stories, right in your MSN feed. Follow AMI on MSN |
By Thomas Caldwell — AMI’s senior editor for mechanical and mobility engineering, covering vehicle electronics, systems integration, electrification, chassis systems, propulsion, and safety policy.