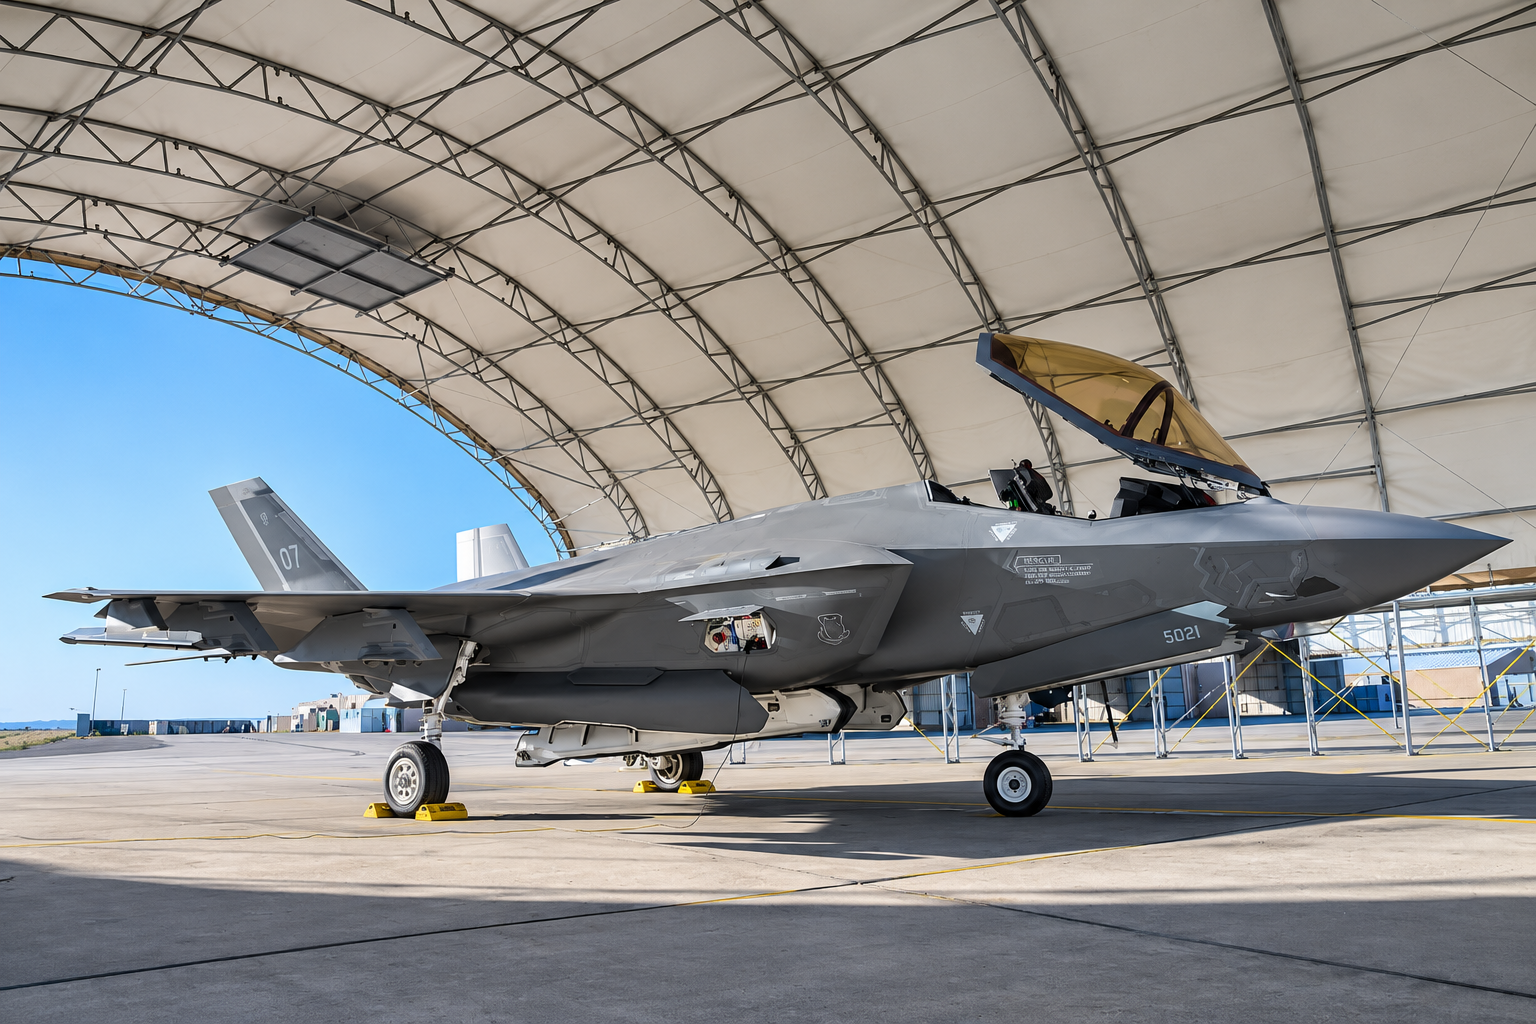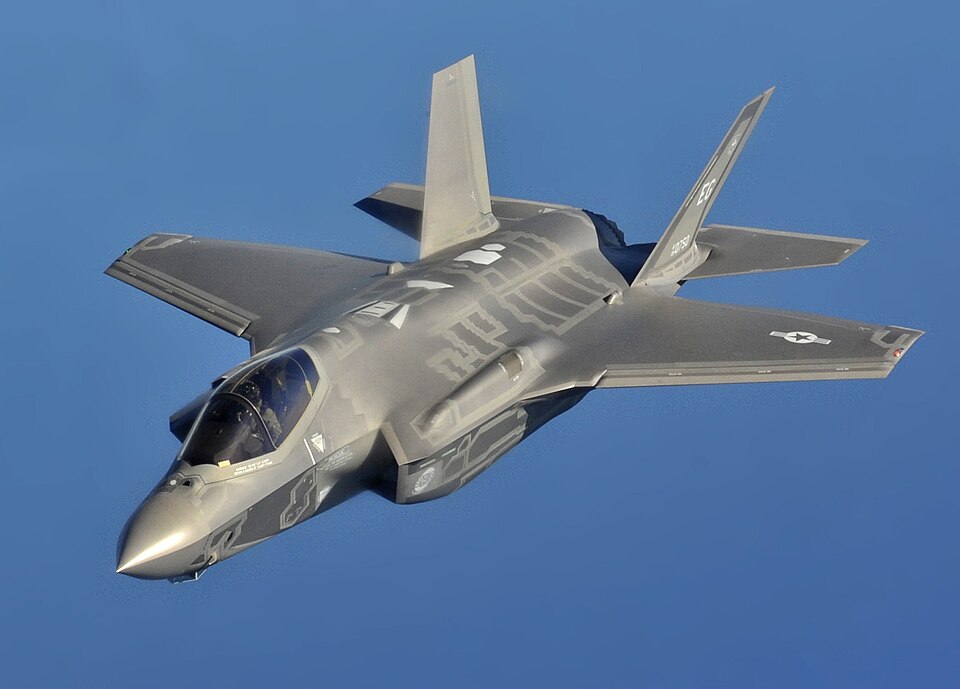
Pentagon Inventories F-35 Parts After 17,000-Component Gap Worth Up to $2.5 Billion
The Pentagon is conducting a full inventory after auditors found that the F-35 program lacked reliable accounting data for more than 17,000 government-owned components undergoing maintenance or repair. The records covered parts estimated at $1.3 billion as of March 2026, but their potential value could reach $2.5 billion once missing cost information and other acquisition expenses are included.

The 17,000 figure is an accounting gap, not confirmation that every component has been physically lost. The immediate problem is that the F-35 program office cannot reliably use its records to establish the components’ locations, values and status. The Defense Contract Audit Agency and the program office are now performing a complete inventory scheduled for completion in March 2027.
Three systems, no continuous property record
The underlying weakness begins with disconnected information systems. The F-35 program’s Enterprise Logistics Management System can record inventory changes in real time, but it does not interact with the property-management systems used by Lockheed Martin and engine manufacturer Pratt & Whitney. Auditors first identified that integration problem in 2022, and it remained unresolved as of August 2026.
Instead of receiving a continuous stream of verified property changes, the program office receives contractor submissions for the shared spare-parts pool every quarter. That interval can leave the government’s record more than three months behind activity in the repair network. A real-time logistics platform offers limited visibility if the contractor systems holding the source data do not communicate with it.
The reporting cycle also has a verification problem. The program office had no procedures for checking contractor information before entering it into the government accounting system. In the December 2025 submission, only 29% of records contained serial numbers and 43% contained national stock numbers. Some components were assigned values of one cent or less, entries auditors said could indicate errors.
Those missing identifiers make reconciliation harder because a part description alone may not establish which individual component moved, entered repair or returned to the pool. Questionable valuations create a second problem: even if a component is listed, the government may still lack a defensible figure for financial reporting. The gap therefore concerns both physical accountability and the reliability of the associated dollar values.
Inventory spending has not produced a verified baseline
The F-35 program office has spent at least $17 million on inventories since fiscal 2020. Its latest inspection still did not fully verify that the listed parts were physically present or reconcile the property records against the actual inventory. That leaves the government without the trusted baseline needed to measure subsequent movements and losses.
The problem predates the current review. A 2019 Defense Department inspector general audit found that officials had not maintained the required government record for F-35 property and instead relied on contractor records. The inspector general called for a complete inventory and a baseline property record, among other corrective actions. The latest findings show why completing an inventory is different from establishing a continuously reliable control system.
The F-35’s sustainment structure raises the stakes. Program participants use a common global pool of government-owned spare parts managed by contractors. A pooled system can move components where operators need them rather than tying every spare to a single aircraft or service. It also depends heavily on common identifiers, timely transactions and consistent property rules across organizations. When those elements are incomplete, the government cannot confidently distinguish a delayed record from an unavailable component.
That uncertainty reaches beyond bookkeeping. Auditors warned that inaccurate property data and inadequate inventory procedures deny the Defense Department information required for reliable financial reporting and combat readiness. Maintenance planners need to know whether a required spare is available, already installed, awaiting repair or merely represented incorrectly in a database. Weak records can complicate those decisions even when the underlying part still exists.
The March 2027 inventory is a starting point
The Defense Department agreed with all four recommendations from the auditors. They include stronger controls for reporting lost spare parts and clearer procedures, training and assignments of responsibility for government-property accounting.
The earlier finding that a prime contractor lost more than one million parts valued above $85 million between May 2018 and October 2022 remains relevant history, but it is a separate measurement from the present 17,000-component accounting gap. The current task is to determine what is physically present, reconcile it with the government’s records and assign supportable values.
Completion of the full inventory in March 2027 should provide a more credible snapshot. Lasting control will require the program to keep that snapshot current after inspectors leave by verifying contractor submissions, resolving missing identifiers and connecting property changes to the government record before another quarterly reporting cycle can make the baseline obsolete.
| More aerospace and engineering stories, right in your MSN feed. Follow AMI on MSN |
By David Whitaker — Associate editor for AMI’s aerospace and drone systems desk, translating flight systems, aircraft programs, spaceflight, and UAV developments into accessible technical stories.